Updated September 14, 2026 to reflect current estate tax exposure and planning considerations.
An irrevocable life insurance trust, often called an ILIT, can play an important role in estate liquidity planning by positioning life insurance proceeds outside the taxable estate.
For families with significant wealth, an ILIT can address two related planning challenges: where life insurance is owned and how liquidity can be positioned outside the taxable estate.
This can be particularly important when substantial wealth is concentrated in real estate, privately held businesses, investment portfolios, or other assets the family may not want to sell simply to meet estate taxes or settlement costs.
The value of the strategy is therefore not simply that an ILIT owns life insurance. It is how the trust, policy, and broader estate plan work together to create liquidity when it is needed.
An ILIT Is More Than a Life Insurance Ownership Structure
The broader planning objective is to position capital outside the taxable estate so it may be available when the family needs liquidity—without automatically requiring the sale of a business, real estate, or other long-term assets.
What Is an Irrevocable Life Insurance Trust (ILIT)?
An irrevocable life insurance trust is designed to own and manage life insurance outside the insured's estate when properly structured and administered.
An irrevocable life insurance trust generally involves three parties:
- Grantor. The person who establishes and funds the trust.
- Trustee. The person or institution responsible for managing the trust according to its terms.
- Beneficiaries. The individuals or other beneficiaries who may receive or benefit from trust property according to the trust terms.
Because an ILIT is irrevocable, the grantor generally cannot simply reclaim assets transferred to the trust or change the trust terms at will.
An ILIT is commonly established to own one or more life insurance policies, with premiums funded through gifts to the trust. Those contributions may use annual gift tax exclusions, a portion of the grantor's lifetime gift and estate tax exemption, or a combination of the two.
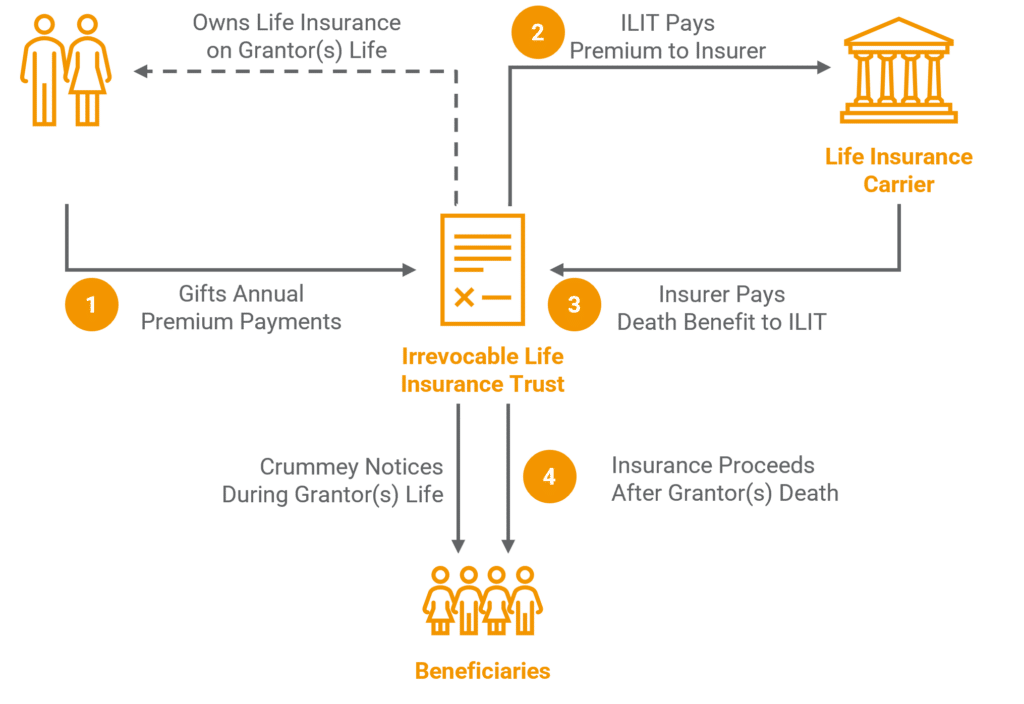
- The grantor makes a contribution to the Irrevocable Life Insurance Trust (ILIT).
- The trustee receives the contribution and, subject to the terms and administration of the trust, uses trust funds to pay premiums on life insurance owned by the ILIT.
- If the policy insures one individual, the death benefit is generally payable to the ILIT at the insured's death. With survivorship life insurance covering two insureds, the death benefit is generally payable after the death of the second insured.
- The trustee receives and administers the life insurance proceeds according to the terms of the ILIT.
2026 Estate Tax Exemption, Annual Gift Exclusion, and Tax Rates
In 2026, the federal estate and gift tax exemption is $15 million per individual, or potentially $30 million for a married couple. The annual gift tax exclusion remains $19,000 per beneficiary. This means an individual can generally give up to $19,000 per recipient in 2026 without using lifetime exemption. Married couples may be able to combine their exclusions and gift up to $38,000 per beneficiary when the applicable requirements are satisfied.
For families with estates above the exemption amount, the top federal estate tax rate remains 40%. Even with the higher exemption, many affluent families may still face estate tax exposure due to business interests, real estate, concentrated investments, or continued asset growth.
Why ILIT Planning Still Matters After the 2026 Tax Law Change
The estate tax exemption did not drop in 2026 as previously expected. However, that does not mean ILIT planning is no longer relevant.
For many families, the core issue is not only the size of the exemption. It is liquidity.
An ILIT can help provide capital at death without requiring heirs to sell a family business, real estate, investment assets, or other illiquid holdings at the wrong time.
How an ILIT Can Provide Estate Liquidity
Life insurance owned by an ILIT can create a source of liquidity outside the insured's taxable estate when the trust and policy are properly structured and administered.
At death, the insurance proceeds are paid to the ILIT as beneficiary of the policy. Because the trustee controls those proceeds according to the terms of the trust, the liquidity does not automatically become part of the estate.
Instead, depending on the terms of the trust and guidance from the family's legal and tax advisors, the trustee may be able to use the proceeds to help address the estate's liquidity needs. For example, the trust may purchase assets from the estate or lend funds to the estate on appropriate terms. The estate can then use the resulting cash to meet taxes, expenses, or other obligations without necessarily forcing the immediate sale of a business, real estate, or other long-term assets.
This distinction is important. The ILIT does not simply “pay the estate tax.” Rather, it can create a separate source of capital that may be coordinated with the estate when liquidity is needed.
The effectiveness of the strategy depends on more than the amount of life insurance. Policy ownership, beneficiary designations, trust provisions, premium funding, trustee responsibilities, and the estate's projected liquidity need should all be coordinated as part of the broader estate plan.
This is why ILIT planning is best approached collaboratively. The estate planning attorney establishes the legal structure, while the family's tax, financial, and insurance advisors help ensure the funding strategy and life insurance remain aligned with the objectives of the estate plan.
Four Elements of an Effective ILIT Strategy
Trust Design
The ownership structure, beneficiaries, trustee powers, and distribution provisions should support the family's broader estate-planning objectives.
Life Insurance Design
The amount, type, and structure of coverage should reflect the family's projected liquidity need and the intended purpose of the insurance.
Premium Funding
Annual exclusion gifts, lifetime exemption, cash flow, and premium requirements should be evaluated together rather than independently.
Ongoing Administration
Trust administration, premium payments, policy performance, and changing estate liquidity needs should be reviewed over time.
Irrevocable Life Insurance Trust (ILIT) Benefits
An ILIT can provide several planning benefits when it is properly structured and coordinated with the broader estate plan. Depending on the family's objectives, these may include:
- Estate liquidity. Life insurance proceeds can create a source of capital that may help address estate taxes, settlement expenses, or other liquidity needs without requiring the immediate sale of long-term assets.
- Potential estate tax efficiency. When properly structured and administered, life insurance owned by an ILIT may be excluded from the insured's taxable estate.
- Greater control over distributions. The trust can establish how and when beneficiaries receive or benefit from life insurance proceeds rather than distributing the entire death benefit outright.
- Inheritance equalization. Life insurance can provide value for some beneficiaries while allowing a business, real estate, or another difficult-to-divide asset to pass to others.
- Potential asset protection. Depending on the trust terms and applicable law, assets retained in the trust may have protections that would not necessarily be available with an outright distribution.
These benefits depend on the trust being properly drafted, funded, and administered. An ILIT should therefore be evaluated as part of the family's broader estate plan rather than as a standalone life insurance arrangement.
When Does an Irrevocable Life Insurance Trust Make Sense?
An ILIT is not necessary for every family. However, it may be worth considering in situations where:
- The estate is currently, or is projected to become, subject to federal or state estate taxes.
- A significant portion of family wealth is concentrated in illiquid assets such as real estate or a closely held business.
- The family wants to create a dedicated source of liquidity without requiring the sale of long-term assets.
- Life insurance proceeds are intended to equalize inheritances when certain assets are difficult to divide.
- The family wants greater control over how and when beneficiaries receive or benefit from life insurance proceeds.
- Existing life insurance is substantial enough that ownership and potential estate inclusion warrant review.
Even for families below the federal estate tax exemption today, continued asset growth, concentrated holdings, state estate taxes, and changes in family circumstances can make it worthwhile to evaluate future liquidity needs before a taxable estate develops.
Funding an ILIT and Crummey Withdrawal Rights
Life insurance premiums owned by an ILIT are often funded through gifts to the trust. Depending on the family's circumstances and the design of the trust, those gifts may use annual gift tax exclusions, a portion of the grantor's lifetime gift tax exemption, or a combination of the two.
When annual exclusions are being used, the trust may provide beneficiaries with temporary withdrawal rights, commonly known as Crummey withdrawal rights. After a contribution is made, the trustee typically notifies the beneficiaries that they have the right to withdraw their share of the contribution during a specified period.
These withdrawal rights can help gifts to the trust qualify as present-interest gifts for purposes of the annual gift tax exclusion. If the withdrawal period expires without a beneficiary exercising the right, the trustee can generally use the contributed funds in accordance with the terms of the trust, including paying life insurance premiums.
Proper administration is important. Contributions, beneficiary notices, withdrawal periods, and premium payments should be coordinated with the estate planning attorney and tax advisor and documented consistently with the terms of the ILIT.
ILIT vs. Personally Owned Life Insurance
Life insurance can provide liquidity whether it is owned personally or by a trust. However, ownership can have a significant impact on whether the death benefit is included in the insured's taxable estate and how the proceeds are controlled after death.
| Consideration | Personally Owned Life Insurance | ILIT-Owned Life Insurance |
|---|---|---|
| Policy Ownership | The insured may retain the ownership rights provided by the policy. | The trust owns the policy and the trustee exercises ownership rights according to the trust terms. |
| Estate Inclusion | When the insured retains incidents of ownership, the death benefit is generally included in the insured's gross estate for federal estate tax purposes. | When properly structured and administered, policy proceeds may be excluded from the insured's taxable estate. |
| Control of Proceeds | Proceeds are paid to the designated beneficiary and are then controlled by that beneficiary, subject to the beneficiary arrangement. | The trustee receives and administers the proceeds according to the terms of the trust. |
| Estate Liquidity | The death benefit can provide capital to beneficiaries, but ownership may affect estate inclusion. | The trust can create a source of capital outside the taxable estate that may be coordinated with estate liquidity needs. |
For families with substantial life insurance coverage, these differences can materially affect both potential estate tax exposure and the amount of liquidity positioned outside the estate.
What If You Already Own a Life Insurance Policy?
An existing life insurance policy can potentially be transferred to an ILIT, but transferring an existing policy involves additional tax and planning considerations that do not generally arise when the ILIT purchases a new policy from inception.
One important consideration is the three-year inclusion rule. If an insured transfers an existing policy on their life to an ILIT and dies within three years of the transfer, the death benefit may still be included in the insured's gross estate for federal estate tax purposes.
The transfer itself may also constitute a gift to the trust, making the value of the policy relevant for gift tax purposes. Depending on the circumstances, transfer-for-value rules and other income tax considerations may also need to be evaluated before ownership is changed.
For these reasons, an existing policy should not simply be retitled to an ILIT without first reviewing the policy, its value, ownership history, and the proposed transfer with the family's estate planning attorney, tax advisor, and life insurance advisor.
In some situations, transferring an existing policy may be appropriate. In others, having the ILIT acquire new coverage may provide a cleaner structure. The appropriate approach depends on the existing policy and the family's broader estate and liquidity objectives.
Common ILIT Planning Mistakes to Avoid
While an ILIT can be an effective estate planning tool, its benefits depend on proper structuring and ongoing administration. Common issues include:
- Improper policy ownership or beneficiary designations. Errors in how a policy is owned or how beneficiaries are designated can undermine the intended estate planning structure.
- Inconsistent trust funding and administration. Premium contributions, trustee responsibilities, and trust records should be coordinated with the terms of the ILIT.
- Failing to properly administer Crummey withdrawal rights. When annual exclusions are being used, contributions and beneficiary notices should be handled consistently with the trust document and guidance from the family's advisors.
- Transferring an existing policy without considering the three-year inclusion rule. Moving an existing policy into an ILIT requires additional analysis before the transfer is completed.
- Allowing the life insurance policy to go unreviewed. Policy performance, funding requirements, guarantees, and the amount of coverage should be reviewed periodically to determine whether the insurance continues to support the trust's objectives.
- Failing to revisit the estate's liquidity needs. Asset values, estate tax exposure, family circumstances, and existing sources of liquidity can change significantly over time.
An ILIT is not a set-it-and-forget-it strategy. Ongoing coordination among the trustee, estate planning attorney, tax advisor, and life insurance advisor helps ensure that both the trust and the insurance continue to function as intended.
Integrating an ILIT Into the Broader Estate Plan
An ILIT is most effective when it is treated as part of the broader estate plan rather than simply as a trust that owns life insurance.
The amount and structure of the insurance should reflect the family's projected liquidity needs, while policy ownership, beneficiary designations, premium funding, and trust administration should remain coordinated with the legal and tax strategy. As the estate grows and family circumstances change, both the liquidity need and the life insurance supporting the ILIT should be reviewed periodically.
For affluent families with significant illiquid wealth, the objective is not simply to keep life insurance outside the taxable estate. It is to create a reliable source of capital that can help preserve flexibility when estate taxes, settlement expenses, or other obligations arise.