A sale to an IDGT can help families with substantial appreciating assets address a difficult estate planning tradeoff: how to transfer future growth outside the taxable estate while retaining sufficient cash flow, financial flexibility, and control over the family's core holdings.
This case study illustrates how one family coordinated a sale to an intentionally defective grantor trust (IDGT) with life insurance to address that challenge.
When the strategy was implemented, the married couple, ages 58 and 56, had a net worth of approximately $160 million concentrated primarily in high-growth, income-producing real estate. The husband remained actively involved in the business, and the couple wanted to retain control of the majority of their real estate holdings.
At the same time, they had several long-term planning objectives. They wanted to transfer future appreciation to their heirs, make substantial charitable bequests, create liquidity for projected estate taxes, and provide the wife with approximately $10 million of additional liquidity if the husband predeceased her.
Based on the assumptions used in the original planning analysis, the couple's projected federal estate tax liability at life expectancy was approximately $50 million after charitable bequests and other estate planning strategies.
Using a Sale to an IDGT to Transfer Future Appreciation
Rather than transferring a large portion of their real estate outright, the couple and their advisors considered a sale to an intentionally defective grantor trust. An IDGT is an irrevocable trust designed so that the grantor is generally treated as the owner for federal income tax purposes while the transferred assets may be outside the grantor's taxable estate when the trust is properly structured and administered.
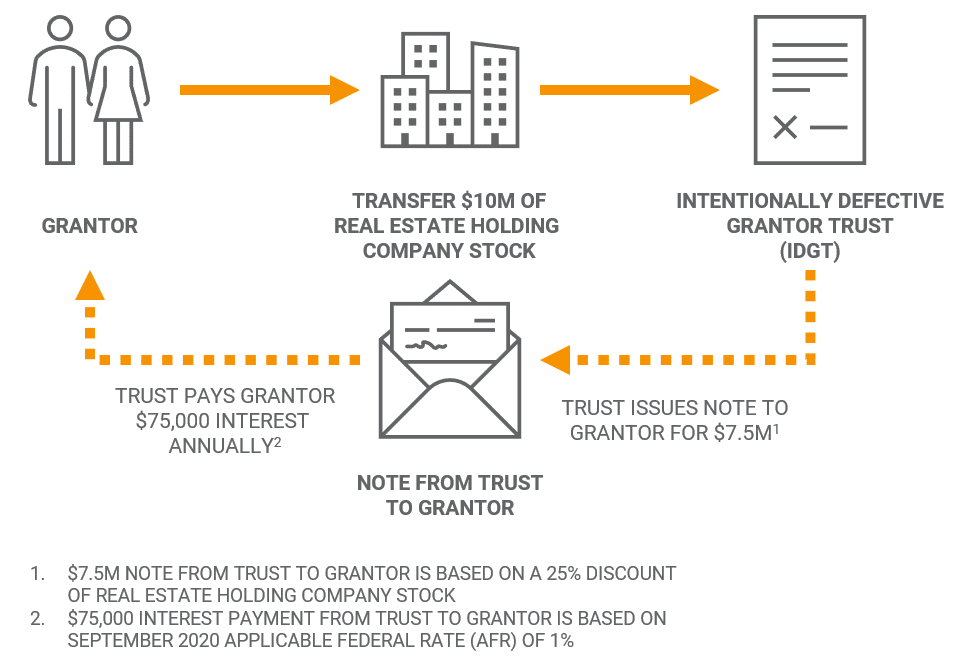
Because transactions between a grantor and a grantor trust are generally disregarded for federal income tax purposes, a properly structured sale can allow appreciating assets to be transferred to the trust in exchange for a promissory note without the sale itself generally being recognized as a taxable sale for federal income tax purposes. The estate planning objective is for future appreciation in the transferred assets above the economic cost of the note to accrue for the benefit of the trust beneficiaries.
In this case, the couple was comfortable committing approximately $10 million of real estate interests to the strategy. A qualified third-party valuation was obtained for interests in the family's real estate holding company. Based on that valuation, the interests transferred in the transaction reflected valuation adjustments applicable to the specific ownership interests being transferred.
The trust purchased the interests in exchange for a 30-year promissory note. When the transaction was implemented in September 2020, the long-term Applicable Federal Rate (AFR) was 1.00%. That historically low rate was an important component of the original economics. A similar transaction implemented today would need to be evaluated using current AFRs, asset values, cash flow assumptions, and other planning considerations.
Using Trust Cash Flow to Support the Strategy
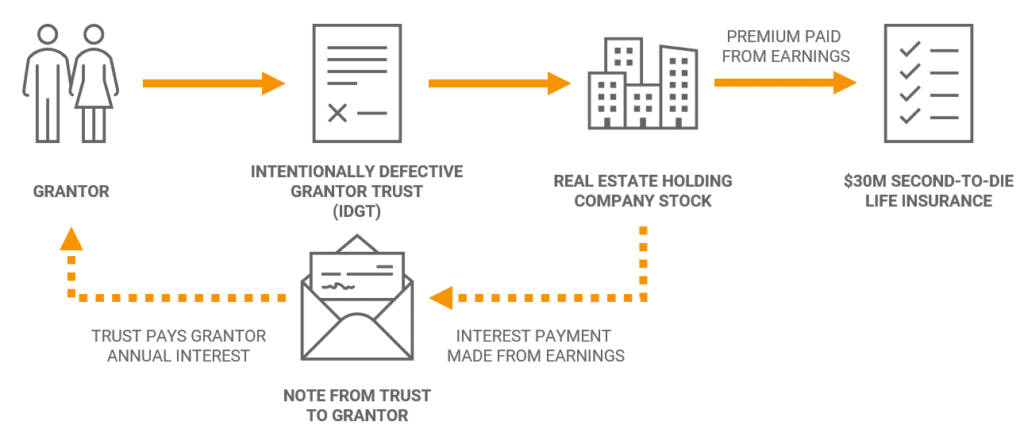
For the transaction to work as intended, the trust needed sufficient economic substance and cash flow to meet its obligations. As part of the original design, the couple made an initial $1 million contribution to the trust using a combination of cash and real estate interests. The contribution provided the trust with additional capital and liquidity during the early years of the strategy.
The real estate interests acquired by the trust were expected to appreciate at approximately 5% annually while generating approximately 6% of annual income. That combination of income and appreciation was central to the planning analysis: current cash flow could help support trust obligations, while future appreciation above the economics of the promissory note could accumulate for the trust beneficiaries.
Under the original 2020 assumptions, the trust made annual interest payments of approximately $75,000 on the note. The actual economics of a sale-to-IDGT transaction depend on the value of the assets transferred, the terms of the note, applicable interest rates, trust cash flow, and the performance of the underlying assets.
Adding Survivorship Life Insurance for Estate Liquidity
The strategy also incorporated a $30 million survivorship life insurance policy owned by the trust. The policy was designed to provide liquidity after both spouses had died, when estate taxes and other settlement obligations could create significant demands on the family's estate.
Under the original design, the annual premium was approximately $222,421. Cash flow generated by the real estate interests held in the trust was expected to help fund the premiums while also supporting the trust's other obligations.
Life insurance was not the reason for implementing the IDGT strategy. Rather, it served a separate but complementary purpose: converting a portion of the trust's ongoing cash flow into a future source of estate liquidity that could support the family's broader estate plan.
Creating Liquidity at the First Death
The survivorship policy addressed liquidity after both spouses had died, but it did not address another important objective: providing additional financial flexibility if the husband died first.
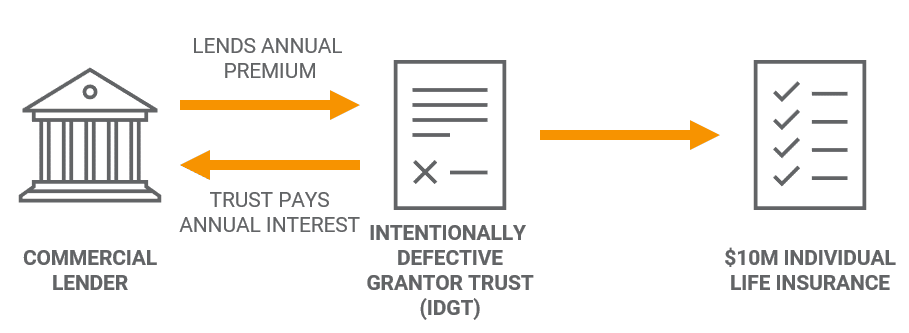
To address that need, the original strategy included $10 million of individual life insurance on the husband. Rather than using additional gifts to fund the premiums, the trust used commercial premium financing. Under the original 2020 design, a lender financed annual premiums of approximately $219,699 for 10 years, while excess cash flow generated by the trust's real estate holdings was expected to cover loan interest.
The strategy also contemplated using accumulated trust resources to repay the premium finance loan in approximately Year 11. That repayment assumption depended on asset performance, trust cash flow, borrowing costs, policy performance, and the availability of sufficient collateral and liquidity.
Premium financing should therefore be viewed as a funding mechanism rather than a source of economic value by itself. Changes in interest rates, collateral requirements, policy performance, or trust cash flow can materially affect the results. A strategy implemented today would require new modeling based on current financing terms and policy assumptions.
Coordinating Liquidity With the IDGT Note
If the husband died while the individual policy remained in force, the $10 million death benefit would provide additional capital to the trust. Depending on the circumstances at that time and the terms of the trust, those proceeds could potentially be used to satisfy trust obligations, including repayment of some or all of the outstanding IDGT note.
Payments received by the grantor or the grantor's estate through satisfaction of the note could create liquidity outside the trust. This was particularly relevant to the family's objective of providing financial resources for the wife if the husband predeceased her.
The structure therefore addressed two different liquidity events. The individual policy was designed to create capital if the husband died first, while the survivorship policy was intended to provide liquidity after both spouses had died, when estate taxes and other settlement obligations were expected to become more significant.
What the Strategy Was Designed to Accomplish
The value of the strategy came from coordinating several planning techniques rather than relying on any one component. The sale to the IDGT, the cash flow generated by the real estate interests, the two life insurance policies, and the premium financing arrangement each served a different purpose.
Under the original planning assumptions, the strategy was designed to:
- Transfer future appreciation. The sale moved selected real estate interests to the trust in exchange for a promissory note, creating the potential for appreciation above the economics of the note to accumulate for the trust beneficiaries.
- Preserve cash flow within the planning structure. Income generated by the real estate interests could help service the IDGT note, fund life insurance premiums, and support other trust obligations.
- Create liquidity at the first death. The $10 million individual policy on the husband was designed to provide capital if he died first, potentially allowing the trust to satisfy obligations while supporting the family's broader liquidity objectives.
- Create estate liquidity at the second death. The $30 million survivorship policy was intended to provide a larger pool of capital when estate taxes and other settlement obligations were expected to arise.
- Limit additional lifetime gifts used for insurance funding. Trust cash flow and, for the individual policy, commercial premium financing were incorporated into the original design to reduce reliance on additional gifts for premium payments.
Important Risks and Planning Considerations
A strategy involving a sale to an IDGT, life insurance, and premium financing requires ongoing coordination. The favorable interest-rate environment in 2020 contributed to the economics of this particular case, but low interest rates alone did not make the strategy successful.
Several variables can materially affect the outcome:
- Asset performance and cash flow: The trust must have sufficient resources to meet note payments, insurance premiums, financing costs, and other obligations.
- Valuation: Interests transferred to the trust should be supported by appropriate valuation analysis based on the specific assets and ownership interests involved.
- Interest rates: Applicable Federal Rates affect the economics of the installment sale, while commercial borrowing rates affect the cost of premium financing.
- Life insurance performance: An ongoing life insurance policy review can help evaluate policy values, funding requirements, and actual performance against the assumptions used when the coverage was originally designed.
- Collateral and financing requirements: Premium financing may require additional collateral, and those requirements can change as loan balances, interest rates, and policy values change.
- Trust administration: The trust, note, insurance policies, distributions, and financing arrangements must be administered consistently with the governing documents and the family's legal and tax planning.
For that reason, this type of strategy should be modeled under multiple scenarios and reviewed periodically with the family's estate planning attorney, tax advisors, investment advisors, insurance advisors, trustee, and lender where applicable.
Coordinating an IDGT Strategy With Life Insurance
This case illustrates how a sale to an intentionally defective grantor trust can be coordinated with life insurance when a family owns appreciating, income-producing assets and has significant future liquidity needs.
The IDGT was intended to transfer future appreciation while the promissory note provided consideration back to the sellers. Income generated by the transferred real estate interests helped support the trust's obligations. Life insurance addressed separate liquidity needs at the first and second deaths, while premium financing provided a funding mechanism for a portion of the insurance strategy.
The specific economics in this case reflected the unusually low interest-rate environment that existed when the strategy was implemented in 2020. A similar strategy considered today should not simply replicate those assumptions. Current asset values, valuations, Applicable Federal Rates, commercial financing costs, policy performance, collateral requirements, estate tax exposure, and family objectives should all be evaluated before implementation.
For families considering life insurance as part of a sophisticated trust or estate liquidity strategy, Mericle & Company works collaboratively with estate planning attorneys, CPAs, investment advisors, trustees, and other professionals to evaluate the insurance design, funding strategy, and long-term liquidity requirements.