This premium financing life insurance case study examines how a family with substantial wealth concentrated in businesses, real estate, and other illiquid assets addressed a difficult estate liquidity question:
Where will the capital come from to meet estate obligations without forcing the sale of assets the family intends to preserve?
Life insurance can provide a source of liquidity at death, but large policies can also require substantial premiums during life. That creates a second planning decision: whether to fund those premiums directly or use outside financing.
In this premium financing life insurance case study, we examine how a high-net-worth family used third-party financing as part of a broader estate liquidity strategy designed to provide more than $20 million of life insurance death benefit while preserving current capital and avoiding the planned sale of core assets.
Premium Financing Is a Funding Mechanism, Not the Planning Objective
The reason for purchasing life insurance should come first. Premium financing changes how the premiums are funded; it does not create the underlying insurance need. Its effectiveness depends on borrowing costs, collateral requirements, policy performance, and a realistic strategy for eventually reducing or repaying the loan.
Client Profile
The client was a married couple in their early 60s with an estimated net worth of approximately $35 million. Like many families in this position, the majority of their wealth was concentrated in illiquid or tax-sensitive assets, including a closely held business, commercial real estate holdings, and a diversified investment portfolio with significant embedded gains.
While their balance sheet was strong, their liquidity position was limited relative to their projected estate tax exposure. Based on the planning assumptions used in the analysis, continued asset growth could create an estate tax liability exceeding $20 million, producing a substantial gap between the family's projected obligations and available liquidity.
The Problem: A Significant Liquidity Gap
The core issue was not simply the projected estate tax exposure—it was how the family would create sufficient liquidity to address it.

For illustration purposes, projections assume 6% annual growth in existing assets and 2% annual growth in the lifetime exemption. These are modeling assumptions, not forecasts of future investment returns or tax law.
Without a structured plan, the family faced the possibility of being forced to sell business interests or real estate holdings at an inopportune time. Liquidating appreciated assets would also introduce additional tax consequences, further reducing the value passed to heirs.
This is a common challenge in estate liquidity planning, where balance sheet strength does not necessarily translate into usable cash at the time it is needed most.
Why Traditional Planning Approaches Fell Short
Before implementing premium financing, the family evaluated several ways to address the projected liquidity need.
Paying life insurance premiums directly was a viable option, but it would have required the family to commit substantial current capital to the insurance strategy. Given the family's concentration in business and real estate assets, they wanted to evaluate whether outside financing could preserve greater financial flexibility.
The use of an irrevocable life insurance trust (ILIT) was also part of the estate planning discussion. An ILIT can help position life insurance outside the insured's taxable estate when properly structured, but the trust's ownership of the policy does not by itself solve the question of how large premiums will be funded.
The family also considered whether to defer the decision. That would preserve current capital in the near term, but continued growth in the business, real estate, and other assets could increase the future liquidity need. The analysis therefore focused on addressing the projected exposure while the family still had flexibility in how the strategy could be structured.
How Premium Financing Life Insurance Works in Practice
After evaluating the alternatives, the family implemented a premium financing strategy to fund the life insurance needed for the projected estate liquidity gap while limiting the amount of current capital committed to premiums.
A survivorship life insurance policy was established and owned by an irrevocable trust as part of the family's estate plan. Rather than funding the premiums entirely with current gifts or other available assets, the trust entered into a financing arrangement with a third-party lender.
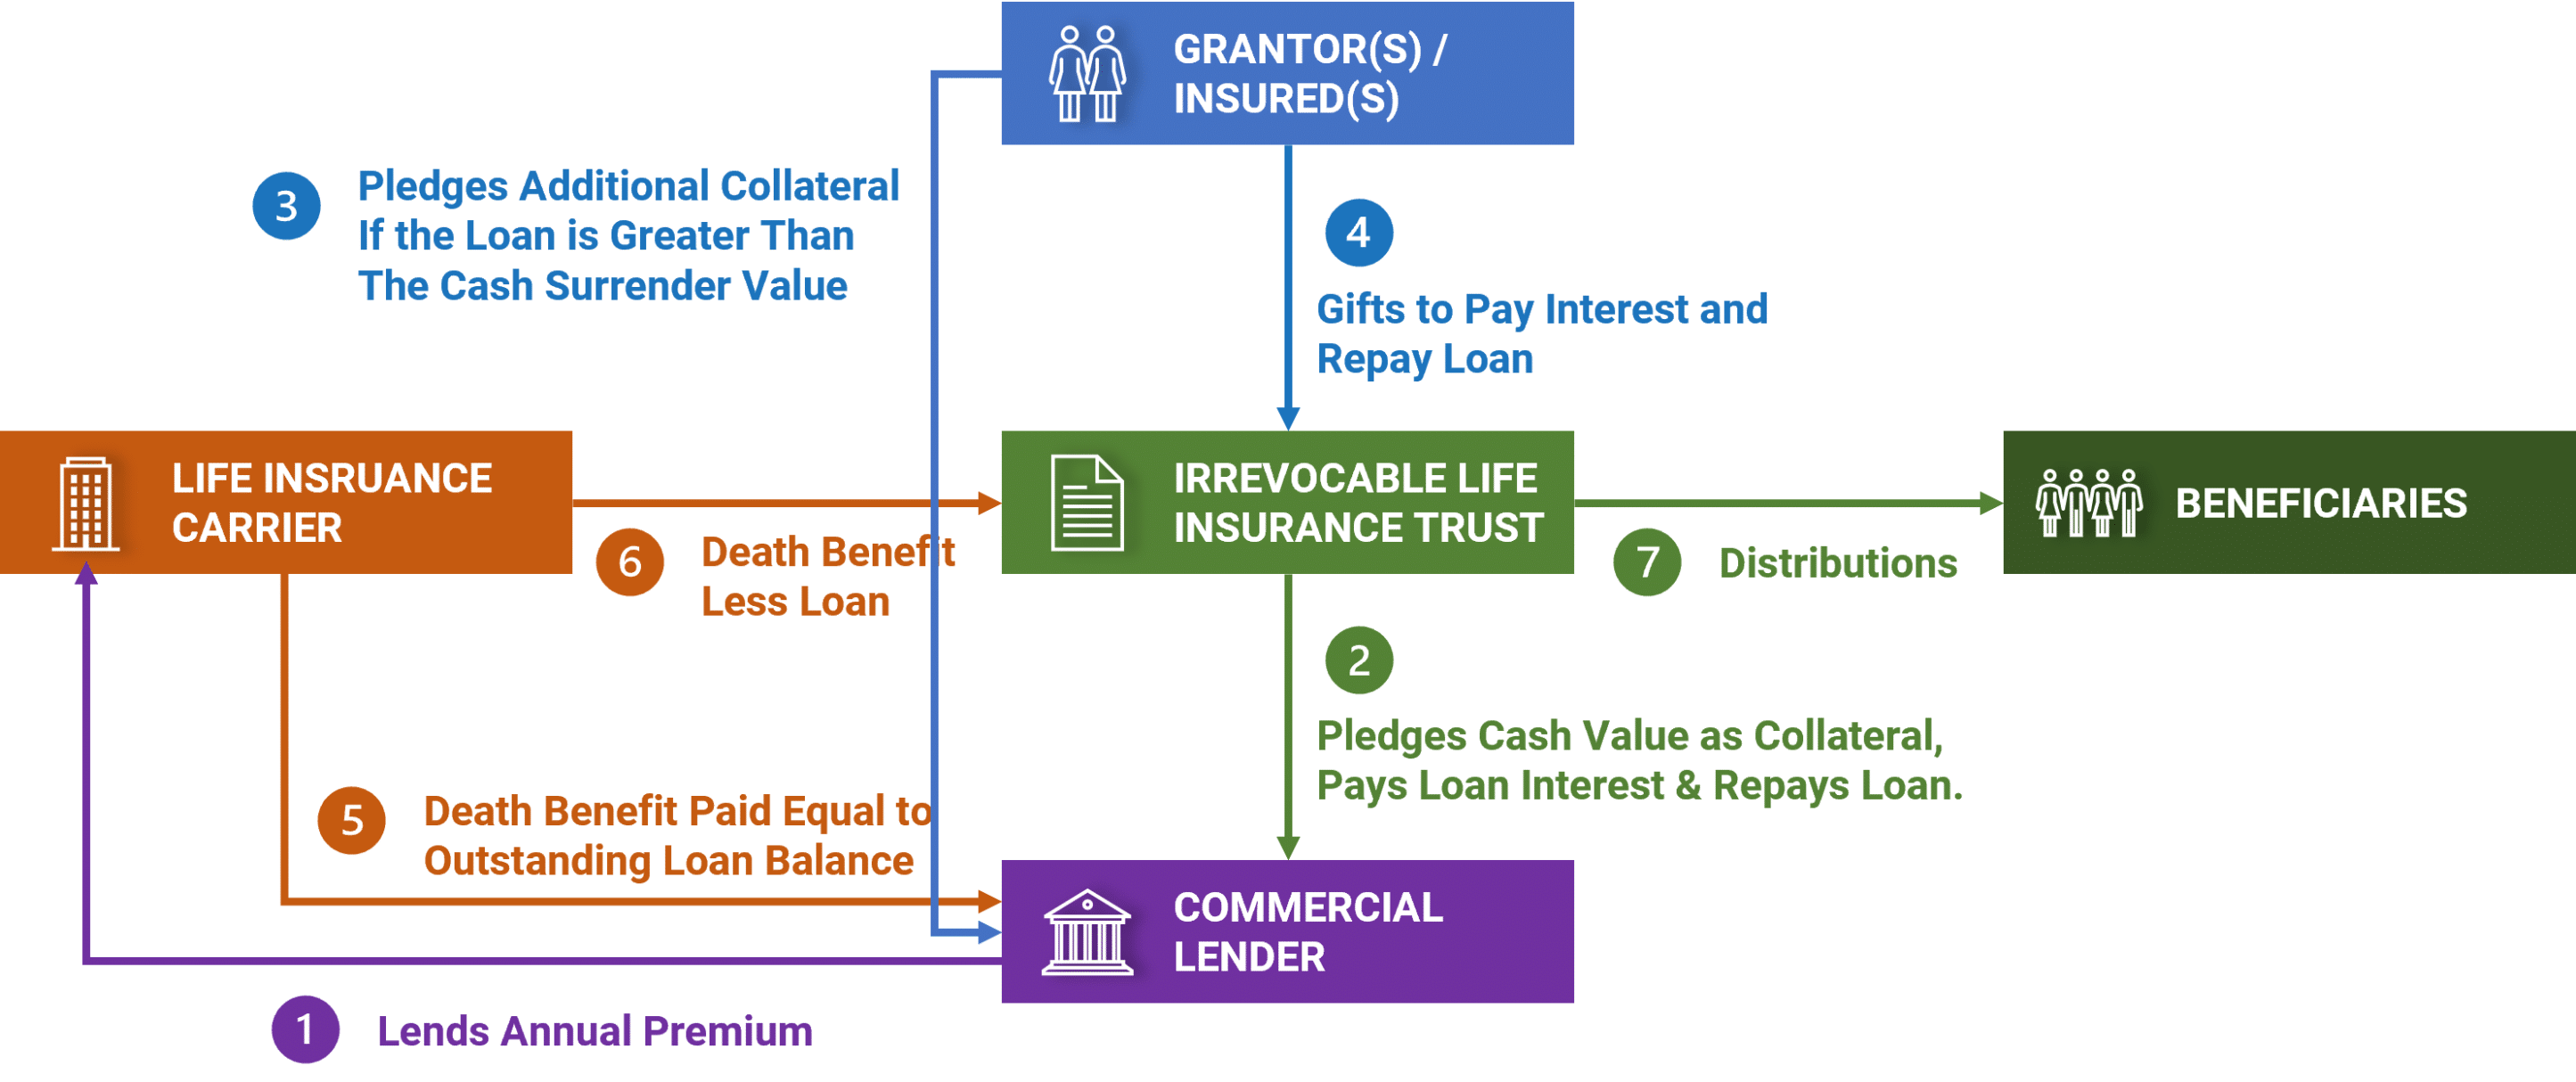
Simplified structure of the premium financing arrangement used to fund life insurance premiums.
The financing arrangement required the family to manage several moving parts over time. Policy cash value supported a portion of the loan, while additional collateral could be required depending on the outstanding loan balance, policy values, interest rates, and lender requirements.
Just as important, the strategy included potential paths for eventually reducing or repaying the debt. Depending on future circumstances, those could include using outside assets following a liquidity event, gradually paying down the loan, or refinancing when appropriate. The family was not relying on a single future event or policy-performance assumption to make the strategy work.
This allowed the family to address the insurance funding need without requiring an immediate sale of the business, real estate, or other core assets. In exchange for preserving that current capital, the family accepted the borrowing costs, collateral requirements, and ongoing oversight associated with the financing arrangement.
Premium Financing vs. Self-Funding Life Insurance
Premium financing was not the only viable way to fund the policy. The family could have paid premiums directly from existing assets or cash flow, eliminating the lender relationship, interest expense, and collateral requirements.
The decision therefore involved a tradeoff between committing more current capital to premiums and accepting the additional costs and risks associated with borrowing.
| Consideration | Self-Funding | Premium Financing |
|---|---|---|
| Current Capital | Requires the family to fund premiums directly from available cash flow or existing assets. | Can reduce the amount of current capital committed directly to premiums while the financing arrangement remains in place. |
| Borrowing Costs | No third-party loan interest or lender-related financing costs. | Introduces interest expense and potentially other financing costs that can change over time. |
| Collateral | Does not require collateral to support a premium-finance loan. | May require collateral beyond policy cash value depending on loan balances, policy values, interest rates, and lender requirements. |
| Ongoing Management | Policy performance and premium requirements still require review, but there is no lender relationship to manage. | Requires ongoing coordination of the policy, loan, interest costs, collateral, lender requirements, and exit strategy. |
| Planning Tradeoff | Uses more current capital but avoids the additional leverage and financing variables. | Preserves more current capital but introduces leverage, borrowing costs, collateral requirements, and financing risk. |
Neither approach is inherently better. The appropriate funding strategy depends on the family's liquidity, asset allocation, cash flow, borrowing capacity, risk tolerance, and long-term objectives.
In this case, the advantage of financing was the ability to preserve more current capital and avoid selling assets the family intended to retain. The disadvantage was the introduction of leverage and additional variables that would need to be managed over time.
Families considering the same decision can explore these tradeoffs in greater detail in our discussion of premium financing vs. paying cash for life insurance.
The Outcome: Creating Estate Liquidity Without a Planned Asset Sale
The resulting life insurance strategy provided more than $20 million of death benefit intended to help address the family's projected estate liquidity need.
Premium financing changed how the family funded that coverage. Rather than committing the full premium amount from current assets or cash flow, the family used third-party financing while continuing to hold the business, real estate, and other assets that were central to its long-term plan.
This distinction is important. The life insurance created the potential source of liquidity at death; the financing provided an alternative way to fund the premiums during life. The financing itself did not create the death benefit or eliminate the economic cost of the insurance.
The strategy also created ongoing obligations. Interest costs, collateral requirements, policy performance, and the outstanding loan would need to be monitored throughout the life of the arrangement. The result therefore depended not only on establishing the policy, but on managing the financing strategy as conditions changed.
Key Risks and Ongoing Management
The case also illustrates why premium financing requires ongoing management rather than a one-time implementation decision. Four areas deserve particular attention throughout the life of the strategy:
Interest Rate Risk
Changes in borrowing costs can materially affect the economics of the strategy and the amount of cash required to service the loan.
Collateral Risk
Policy cash value may not fully support the outstanding loan balance. Additional collateral requirements can change as loan balances, rates, policy values, and lender requirements change.
Policy Performance Risk
If policy values develop differently than illustrated, collateral requirements, funding needs, and the timing of an exit strategy may also change.
Financing & Exit Strategy Risk
Lender terms and credit conditions can change, and future financing should not be assumed to remain available indefinitely. The strategy should include realistic alternatives for reducing or repaying the loan.
These variables should be reviewed periodically through updated policy analysis, loan modeling, and collateral evaluation. A life insurance policy review can also help determine whether the policy continues to perform as expected within the broader financing strategy.
When Premium Financing May Be Appropriate
Premium financing is generally most relevant for families with substantial life insurance needs, strong balance sheets, and sufficient collateral capacity to support a borrowing strategy over time.
It may be particularly useful when wealth is concentrated in businesses, real estate, or other assets the family prefers not to sell or reposition simply to fund insurance premiums. Reliable cash flow, a long planning horizon, and the ability to absorb changing interest and collateral requirements are also important.
Most importantly, financing should support a clearly defined insurance and estate liquidity need. The availability of financing alone is not a reason to purchase additional life insurance or assume leverage.
Coordinating Premium Financing With the Broader Estate Plan
This case illustrates how premium financing can be used as one component of a broader estate liquidity strategy. The life insurance addressed the projected need for liquidity at death, while financing provided an alternative way to fund the premiums without requiring an immediate sale of core assets.
That flexibility came with additional obligations. Borrowing costs, collateral, policy performance, lender requirements, and the eventual repayment of the loan all needed to remain part of the planning process.
For families considering a similar approach, the analysis should begin with the underlying estate liquidity need and then compare available funding strategies under realistic assumptions. The financing structure should support the insurance strategy—not determine whether the family needs the insurance in the first place.