This case study is hypothetical and is provided for educational and illustrative purposes only. Individual circumstances, tax considerations, and life insurance results will vary.
Mike and Carol are 59 and 57 and have built an estate worth approximately $25 million. They have three adult children and want to preserve as much of their wealth as possible for the next generation.
At first glance, their current estate may not appear to create a significant federal estate tax problem under today's exemption. But their current net worth tells only part of the story.
Approximately $18 million of Mike and Carol's wealth consists of privately held business interests and real estate. While those assets may continue to appreciate over time, they may not provide readily available cash when their estate eventually needs liquidity.
That creates two related planning questions:
- How large could their taxable estate become over the next 20 to 30 years?
- If an estate tax or other significant settlement obligation arises, where will the cash come from to pay it?
Rather than waiting for those questions to become urgent, Mike and Carol decided to evaluate their future estate exposure and begin planning for the liquidity their family may eventually need.
Estate Planning Assumptions
For purposes of the analysis, Mike and Carol's planning team started with the following assumptions:
- Mike is age 59 and Carol is age 57.
- Their current estate is approximately $25 million.
- Approximately $18 million consists of privately held business interests and real estate.
- They have three adult children.
- They expect to retain their business and real estate interests rather than make significant lifetime transfers of those assets today.
- Their estate is expected to continue appreciating over their lifetimes.
The objective was not simply to determine whether Mike and Carol would owe estate tax under current law. The more important question was how their estate could evolve over time—and whether sufficient liquidity would be available when their family eventually needed it.
Projecting the Future Estate Liquidity Gap
Estate planning for affluent families should generally consider where an estate may be headed, not simply what it is worth today.
For purposes of this analysis, Mike and Carol's $25 million estate was projected forward to their joint life expectancy. Based on the assumptions used in the model, their estate could grow to approximately $68.3 million.
For modeling purposes, the analysis holds the federal lifetime estate and gift tax exemption constant over the projection period rather than assuming future inflation adjustments or changes in tax law. This simplifying assumption is intended to isolate the effect of estate growth and the planning strategies being compared; it is not a prediction of the exemption that will apply in the future.
At a 40% federal estate tax rate, the model estimates an estate tax liability of approximately $3.8 million.
For a family whose wealth is concentrated in a privately held business, real estate, or other illiquid assets, the amount of the tax is only one part of the problem. The other question is how the estate would generate the cash necessary to pay it.
That potential mismatch between estate obligations and readily available assets is the estate liquidity gap.
Mike and Carol wanted to address that potential gap without relying on their children to sell valuable assets after their deaths. Their planning team therefore evaluated whether an irrevocable life insurance trust funded with survivorship life insurance could create a dedicated source of future liquidity.
Why an ILIT Was Considered for the Estate Plan
Mike and Carol's planning objective was not simply to reduce their projected estate tax. They also wanted to create a reliable source of liquidity for their family without requiring the future sale of their business interests or real estate.
One strategy their planning team evaluated was an irrevocable life insurance trust (ILIT) funded with survivorship life insurance.
When properly structured and administered, an ILIT can own life insurance outside of the insureds' taxable estates. At the death of the second insured, the trust receives the policy proceeds and administers them according to the terms of the trust.
This can create a pool of liquidity outside the taxable estate that may be available to support the family's broader estate plan. Depending on the trust design and circumstances at the time, that liquidity could help beneficiaries acquire assets from the estate, provide funds through permitted transactions with the estate, or otherwise reduce pressure to sell illiquid assets at an unfavorable time.
For Mike and Carol, this was particularly important. Approximately $18 million of their current wealth was concentrated in privately held business interests and real estate. They wanted to retain those assets during their lifetimes while creating a separate source of liquidity for their children.
The ILIT addressed the ownership structure, but it did not answer two equally important questions: how much life insurance should the trust own, and how should the premiums be funded?
The planning team therefore modeled a $10 million survivorship life insurance policy and compared several premium-funding strategies to determine how the design could affect annual cash flow, lifetime gifting, and the amount ultimately transferred to Mike and Carol's heirs.
Designing the Life Insurance Strategy
Once Mike and Carol decided to evaluate an ILIT, the next step was determining how life insurance might fit within the overall estate plan.
The planning team modeled a $10 million survivorship life insurance policy owned by the ILIT. Survivorship life insurance insures two people and generally pays the death benefit after the death of the second insured. Survivorship life insurance insures two people and generally pays the death benefit after the death of the second insured. Because the estate liquidity need for a married couple often arises after the death of the surviving spouse, survivorship coverage can be particularly useful when the primary objective is creating liquidity for the next generation.
The $10 million death benefit was not selected simply because Mike and Carol's projected estate tax was approximately $3.8 million. Estate liquidity planning may involve more than replacing a projected tax liability dollar for dollar. The appropriate amount of coverage can depend on the family's objectives, projected estate growth, available liquid assets, existing life insurance, future expenses, and the amount of liquidity the family wants available to preserve other assets.
After establishing the amount of coverage to model, the next question was how to fund the policy.
Comparing Premium-Funding Strategies
The same $10 million death benefit could be funded using several different premium-payment schedules. Each approach creates a different balance between annual cash flow, the number of years premiums are paid, total projected premiums, and the present value of those payments.
Mike and Carol's planning team compared five funding approaches, ranging from a shorter 10-year payment schedule to premiums extending through age 100.

The analysis illustrates why the lowest annual premium is not necessarily the lowest-cost strategy.
In this case, the 10-pay design required the largest annual commitment among the scheduled-payment alternatives, but it produced the lowest modeled present-value cost at approximately $1.64 million. The 20-pay design reduced the annual premium and produced a modeled present-value cost of approximately $1.73 million.
Extending premiums over a longer period reduced the annual cash-flow requirement further, but increased the modeled present-value cost. Premiums paid to life expectancy produced a present-value cost of approximately $1.91 million, while payments extending to age 100 increased the modeled present-value cost to approximately $2.17 million.
The comparison does not mean that the strategy with the lowest present-value cost is automatically the best choice. A shorter funding period requires greater annual cash flow and may require larger transfers to the ILIT during those years. A longer funding period may reduce the annual transfer requirement but expose the policyholder to premium obligations for a longer period.
For Mike and Carol, the premium analysis therefore had to be considered together with another important part of the ILIT design: how assets would be transferred to the trust to pay the premiums.
Funding the ILIT: Annual Exclusion Gifts vs. Lifetime Exemption
Once the premium designs were modeled, Mike and Carol's planning team needed to determine how the premiums would be funded inside the ILIT.
Because the ILIT is a separate trust, Mike and Carol would generally make gifts to the trust, and the trustee would use those funds to pay the life insurance premiums. How those gifts are structured can affect both the amount that can be transferred each year and the amount of lifetime gift and estate tax exemption used.
Using Annual Exclusion Gifts
In 2026, the federal annual gift tax exclusion is $19,000 per recipient. With three children, Mike and Carol could potentially transfer up to $114,000 annually using both spouses' annual exclusions, assuming the gifts are properly structured to qualify for the exclusion.
That amount is significant, but it creates an important constraint. If the annual premium exceeds the amount that can be transferred using annual exclusions, Mike and Carol must decide how to fund the difference.
One option is to select a premium schedule that keeps annual contributions closer to the available annual exclusions. Another is to make additional gifts to the ILIT that use a portion of their lifetime gift and estate tax exemption.
Using a Portion of the Lifetime Exemption
Mike and Carol were not limited to annual exclusion gifts. They could also make larger gifts to the ILIT and apply a portion of their available lifetime gift and estate tax exemption to those transfers.
Using lifetime exemption can provide greater flexibility in funding the policy, particularly when a shorter premium-payment period requires contributions above the annual exclusion amount. But using exemption today also means that portion of the exemption is no longer available for other lifetime transfers.
For a family with substantial business and real estate interests, that tradeoff matters. Mike and Carol may eventually want to use their exemption for other planning strategies involving appreciating assets. The decision therefore should not be based on the life insurance policy in isolation.
A Combination Approach
The planning team also evaluated a combination strategy: use available annual exclusion gifts and apply a portion of Mike and Carol's lifetime exemption when additional contributions are needed to support the selected premium schedule.
This approach can provide greater flexibility. Rather than allowing the annual exclusion amount alone to dictate the insurance design, the family can evaluate the policy funding schedule, cash-flow requirements, use of lifetime exemption, and long-term estate objectives together.
For Mike and Carol, the question became whether using some lifetime exemption to fund the ILIT more efficiently could ultimately produce a better estate-planning result than limiting contributions to annual exclusion gifts alone.
Comparing the Estate Planning Outcomes
With the insurance and gifting strategies established, Mike and Carol's planning team compared how each approach could affect their projected estate and the amount ultimately transferred to their heirs.
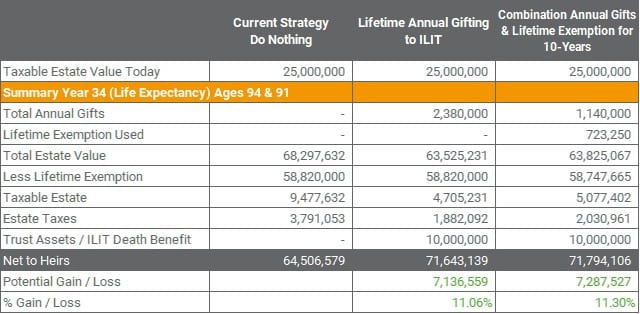
The analysis compared three scenarios: maintaining their current strategy without the ILIT, funding the ILIT primarily through lifetime annual gifts, and using a combination of annual gifts and lifetime exemption.
What the Analysis Shows
The modeled results illustrate that the value of the strategy is not limited to providing a $10 million life insurance death benefit. The way the policy is owned and funded can also affect the size of the taxable estate and the amount ultimately transferred to heirs.
Under the current strategy, Mike and Carol's projected estate grows to approximately $68.3 million. Based on the assumptions used in the model, approximately $9.5 million would be subject to federal estate tax, resulting in an estimated $3.8 million estate tax liability and approximately $64.5 million of net wealth transferred to their heirs.
Using annual exclusion gifts to fund the ILIT changes the projected outcome. The life insurance proceeds are modeled outside Mike and Carol's taxable estate, while the cumulative gifts used to fund the trust also reduce the assets remaining in their estate. Under this scenario, the model projects approximately $71.6 million of net wealth transferred to their heirs—about $7.1 million more than under the current strategy.
The combination strategy produces a similar but slightly higher modeled result. By using annual exclusion gifts together with a portion of Mike and Carol's lifetime exemption, the policy can be funded over a shorter period while reducing the amount remaining in their taxable estate. The model projects approximately $71.8 million of net wealth transferred to their heirs, an improvement of roughly $7.3 million compared with the current strategy.
These results should not be interpreted to mean that using more lifetime exemption is always preferable. The difference between the two ILIT strategies is relatively small, and lifetime exemption is a valuable planning resource that may have other uses. For Mike and Carol, the decision depends not only on the projected inheritance but also on cash flow, future gifting objectives, policy funding requirements, and how they expect to use their remaining exemption.
The Recommended Strategy
After reviewing the alternatives, Mike and Carol's planning team recommended a combination approach that coordinated the life insurance design with their broader gifting and estate-planning objectives.
The ILIT would own a $10 million survivorship life insurance policy designed to create liquidity after the death of the second spouse. Mike and Carol would use available annual exclusion gifts to help fund the trust and, when necessary, use a portion of their lifetime gift and estate tax exemption to support contributions above the annual exclusion amount.
This approach allowed the insurance funding decision to be based on the economics of the policy rather than requiring the annual exclusion amount alone to determine the premium schedule. It also provided greater flexibility to consider a shorter funding period while coordinating the transfers with Mike and Carol's broader estate plan.
That distinction was important. The premium analysis showed that extending payments over a longer period could reduce the annual contribution requirement, but it also increased the modeled present-value cost of the premiums. Using a portion of Mike and Carol's lifetime exemption gave the planning team greater flexibility to consider a shorter funding schedule while still coordinating the transfers with their overall estate plan.
Under the assumptions used in the model, the combination strategy produced approximately $71.8 million of projected net wealth to heirs, compared with approximately $64.5 million under the current strategy. That represents a modeled improvement of approximately $7.3 million.
But the projected increase in wealth transferred was not the only reason for the recommendation. The strategy also created a separate source of liquidity outside Mike and Carol's taxable estate, reduced the family's dependence on selling illiquid assets after their deaths, and provided a defined funding strategy that could be reviewed as their estate, tax law, and financial circumstances changed.
Importantly, the recommendation was based on the assumptions used in this particular case. Changes in policy performance, interest rates, estate growth, tax law, gifting objectives, or Mike and Carol's financial circumstances could change the appropriate strategy. The plan would therefore require ongoing review rather than being treated as a one-time decision.
What This Case Study Illustrates
Mike and Carol's situation illustrates several principles that can be important when life insurance is incorporated into an estate plan.
Today's Estate Value Is Only the Starting Point
An estate that does not create significant federal estate tax exposure today may look very different decades from now. For families with appreciating businesses, real estate, or investment assets, projecting future estate value can reveal risks that are not apparent from the current balance sheet.
Estate Tax Exposure and Estate Liquidity Are Different Problems
Estimating a future estate tax liability is only part of the analysis. Families also need to consider where the cash will come from when taxes and other obligations become due. This is particularly important when a substantial portion of the family's wealth is concentrated in assets that may be difficult or undesirable to sell.
Estate liquidity planning can help families evaluate that potential mismatch before it becomes an immediate problem.
Life Insurance Design and Trust Funding Should Be Evaluated Together
Establishing an ILIT and selecting a life insurance policy are only part of the planning process. Premium schedules, annual exclusion gifts, use of lifetime exemption, policy economics, and the family's other gifting objectives can materially affect how the strategy is structured.
The goal is not necessarily to minimize a single number—such as the annual premium or use of lifetime exemption—but to coordinate the different components of the plan around the family's broader objectives.
The Strategy Requires Ongoing Review
Estate values change. Tax laws change. Life insurance policies may perform differently than originally illustrated, and a family's objectives can evolve over time.
For that reason, an estate-planning life insurance strategy should not be treated as a one-time transaction. Periodic life insurance policy reviews can help determine whether the coverage, funding strategy, and policy performance remain aligned with the purpose for which the insurance was originally acquired.
Planning for Future Estate Liquidity
For affluent families, the estate-planning question is often not simply whether an estate tax exists today. The more useful questions are what the estate may be worth in the future, how much of that wealth will remain illiquid, and where the family will obtain liquidity when it is eventually needed.
An ILIT funded with appropriately designed life insurance can be one tool for addressing that challenge. The appropriate structure, however, depends on the family's assets, objectives, gifting strategy, existing estate plan, and the economics of the life insurance being considered.
Mericle & Company works with families and their legal and tax advisors to evaluate life insurance within the broader estate-planning process. Contact us to discuss how life insurance may fit within your estate liquidity strategy.