Changes in non-guaranteed policy assumptions can materially affect the long-term performance of an existing universal life insurance policy—even when the policy remains in force and premiums have been paid as planned.
This case study illustrates how a change in the current interest-crediting rate affected the projected performance of a $1.5 million universal life insurance policy and why reviewing an existing policy before a problem becomes immediate can provide the policy owner with more options.
Background: A $1.5 Million Universal Life Insurance Policy
In 2008, Michael sold his successful manufacturing company at age 52. As part of his estate planning, his attorney recommended acquiring $1.5 million of life insurance to help provide liquidity for the eventual transfer of his estate to his three children.
Michael applied for a current-assumption universal life insurance policy and qualified for a Preferred Plus underwriting classification. The policy was issued with an annual premium of $19,161.
An irrevocable life insurance trust (ILIT) was established as the owner and beneficiary of the policy so that the coverage could support Michael's broader estate-planning objectives.
By 2021, Michael had owned the policy for approximately 13 years. Although the coverage remained in force, the assumptions underlying its projected performance had changed. Michael engaged us to review the policy and evaluate whether it remained reasonably positioned to accomplish its intended purpose.
Starting the Universal Life Insurance Policy Review
To understand how the policy had changed, we began by obtaining two illustrations from the insurance carrier:
- The original illustration issued when the policy was purchased, and
- A current in-force illustration using the existing $19,161 annual premium.
Comparing the two illustrations allowed us to evaluate the policy's actual position years after issue rather than relying on the assumptions used when the coverage was originally purchased.
The comparison revealed an important difference: the current interest-crediting rate used in the policy illustration was substantially lower than the rate assumed in the original illustration. That change had a significant effect on the policy's projected cash values and longevity.
What the Original Policy Illustration Projected
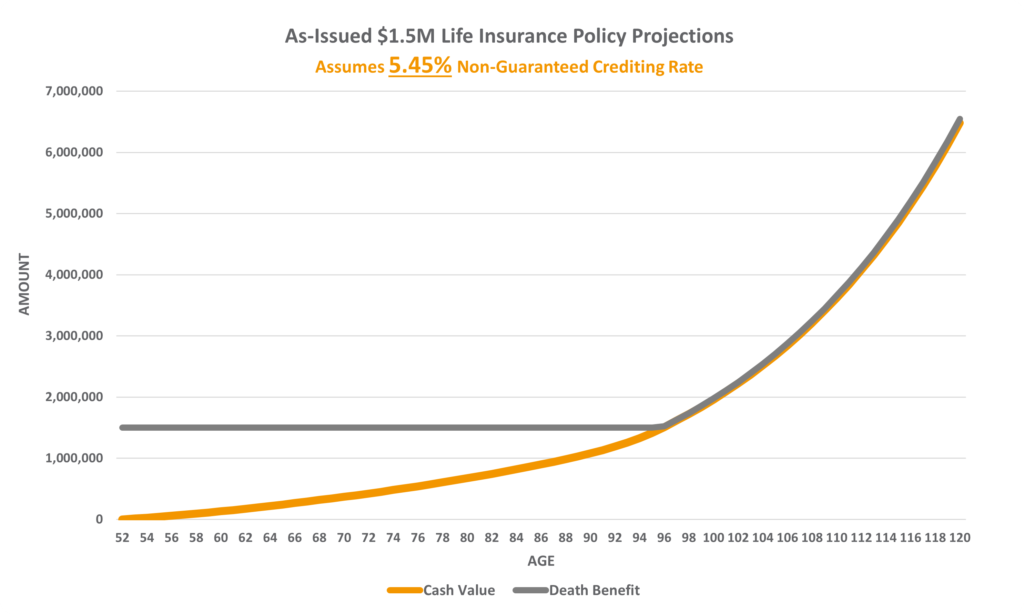
When the policy was issued in 2008, the original illustration projected future policy performance using a 5.45% interest-crediting rate. Because this was a non-guaranteed assumption, the illustrated values depended in part on the policy continuing to receive interest credits at the rate shown.
Based on the assumptions used in the original illustration:
- The policy was illustrated using a 5.45% interest-crediting rate,
- The $1.5 million death benefit was projected to begin increasing at approximately age 96 as illustrated policy values exceeded the initial death benefit, and
- Projected policy value approached $2 million by age 100.
These values were projections rather than guarantees of future policy performance. The actual results would depend on the policy's contractual provisions, premiums paid, interest credited, policy charges, and other factors over time.
The original illustration nevertheless provides an important benchmark. It shows the assumptions under which the policy was initially evaluated and allows those assumptions to be compared with the policy's position years later.
What the Updated In-Force Illustration Revealed
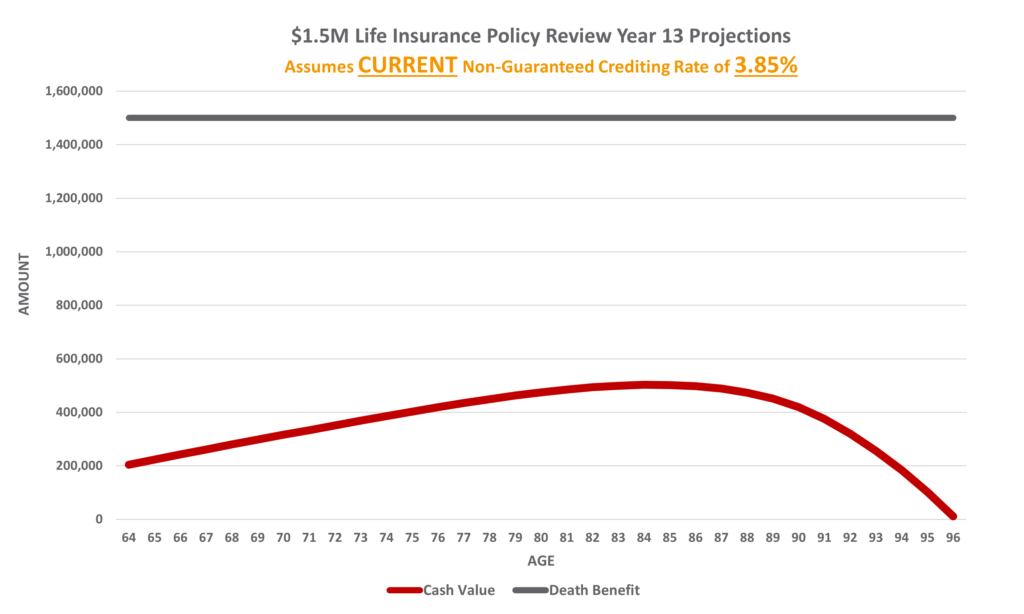
By 2021, the current interest-crediting rate used in the policy illustration had declined from the 5.45% rate shown in the original illustration to 3.85%.
That change did not mean the policy had failed or that it was about to lapse. The $1.5 million death benefit remained in force. However, the updated in-force illustration showed that the policy's long-term projected performance had changed materially.
Based on the policy's current values, the existing $19,161 annual premium, and the assumptions used in the updated illustration:
- The policy was illustrated using a current interest-crediting rate of 3.85%,
- The accumulation of projected policy values was substantially lower than shown in the original illustration, and
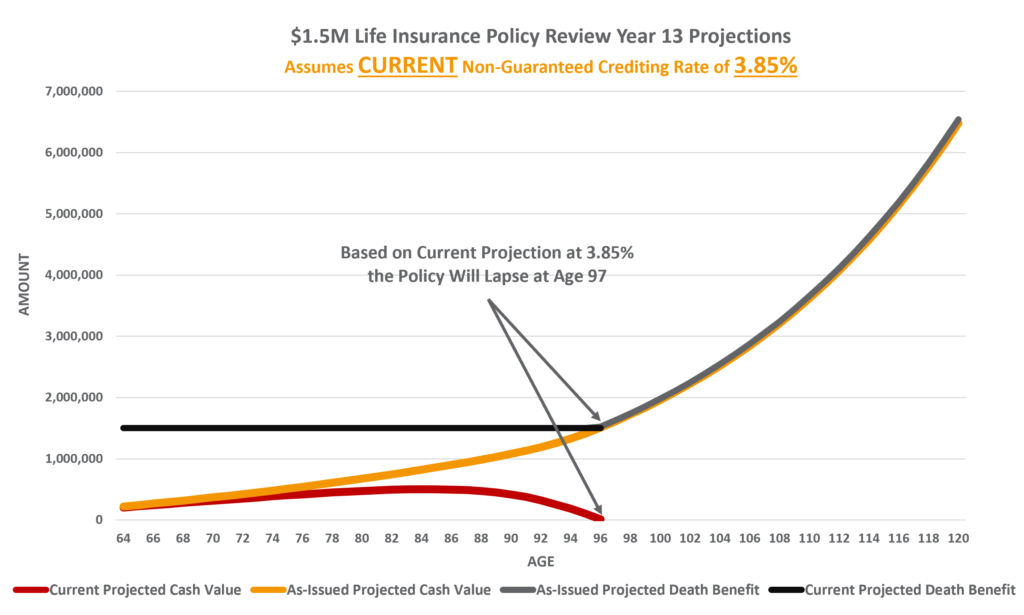
- Instead of the death benefit beginning to increase at approximately age 96, the policy was projected to lapse at approximately age 97.
The difference demonstrates why an existing universal life policy cannot be evaluated solely by confirming that it is currently in force. A policy can appear healthy today while an in-force illustration identifies a potential funding problem many years in the future.
It is also important to distinguish an illustrated lapse from a guaranteed outcome. The age-97 lapse was a projection based on the policy's values and assumptions at the time of the 2021 review. Future interest-crediting rates, policy charges, premium payments, and other factors could produce different results.
What Would Be Required to Maintain Coverage to Age 100?
The updated in-force illustration showed that continuing the existing $19,161 annual premium under the assumptions used at the time of the review was projected to maintain the policy to approximately age 97.
Because Michael's objective was to maintain the death benefit for life, we also evaluated what changes could improve the policy's projected durability.
Based on the policy's values and assumptions at the time of the 2021 review, there were two potential ways to extend the projected coverage to age 100:
- Increase the annual premium, or
- Reduce the death benefit to an amount that could be supported by the existing funding strategy.
Neither approach was automatically the appropriate solution. Increasing the premium would require an additional financial commitment, while reducing the death benefit could affect the amount of estate liquidity available to Michael's beneficiaries.
The important point was that the issue had been identified well before the policy was projected to lapse. That gave Michael time to evaluate the existing policy, consider changes to its funding or death benefit, and compare other available alternatives without being forced to make an immediate decision.
What Options Did the Policy Review Identify?
The policy review did not indicate that Michael needed to make an immediate change. Instead, it identified a developing long-term funding issue while there was still time to evaluate multiple alternatives.
At the time of the 2021 review, the analysis included several potential approaches.
Option 1: Maintain the Existing Policy and Continue Monitoring It
Although the policy was no longer projected to perform as shown in the original illustration, the coverage remained in force and the projected lapse was still many years away.
One option was therefore to continue paying the existing $19,161 annual premium and monitor the policy through periodic in-force illustrations. This would allow Michael to evaluate future changes in policy values, interest-crediting rates, charges, and projected policy durability before deciding whether an adjustment was necessary.
Option 2: Increase Funding to the Existing Policy
Another option was to increase the annual premium. Based on the policy values and assumptions used in the 2021 review, an annual premium of approximately $20,672 was illustrated as sufficient to maintain the existing coverage to age 100.
This represented an increase of approximately $1,500 per year compared with the existing premium. Importantly, however, the result was based on the assumptions used in that illustration. It was not a guarantee that the policy would remain in force to age 100 unless supported by applicable contractual guarantees.
Additional in-force illustrations could also be used over time to determine whether the funding requirement changed as the policy's actual experience developed.
Option 3: Adjust the Existing Death Benefit
If maintaining the $1.5 million death benefit was no longer necessary, reducing the coverage could potentially lower the amount of funding required to support the policy.
That alternative would need to be considered in the context of Michael's estate plan. Because the policy was intended to provide liquidity for his beneficiaries, reducing the death benefit solely to improve policy performance could undermine the planning objective for which the coverage was originally purchased.
Option 4: Evaluate Alternative Coverage
The review also considered whether alternative life insurance coverage might better accomplish Michael's objectives. At the time, other policies were available with different premium requirements, guarantees, and policy structures.
Evaluating replacement coverage did not mean the existing policy should automatically be surrendered or exchanged. A replacement analysis would need to consider Michael's current age and health, the existing policy's values and tax characteristics, the guarantees and provisions that would be lost, the terms of the proposed coverage, and the costs and risks associated with starting a new contract.
If a replacement were ultimately appropriate, a properly structured Section 1035 exchange might allow eligible policy values to be transferred to another life insurance contract without recognizing gain at the time of the exchange. The tax treatment and mechanics would depend on the facts of the transaction and should be evaluated before making a change.
The Value of Identifying the Problem Early
The most important result of the review was not the selection of a particular alternative. It was discovering a potential long-term problem while Michael still had time to respond to it.
At the time of the review, the policy remained in force, the existing premium was manageable, and the projected lapse was decades away. That created flexibility. Michael could continue monitoring the policy, increase funding, consider a change to the death benefit, or evaluate alternative coverage.
Waiting until policy values had deteriorated substantially or the projected lapse was much closer could have reduced those options. The insured would also be older, and changes in health could affect the availability or cost of alternative coverage.
This is one of the primary reasons an existing universal life policy can benefit from a periodic life insurance review. The objective is not simply to identify a policy that is already in trouble. It is to identify changes in projected performance early enough that the policy owner can evaluate the available options deliberately.
Universal Life Insurance Policy Review Case Study: Conclusion
This case study demonstrates why the current status of a universal life insurance policy does not necessarily tell the full story. Michael's $1.5 million policy remained in force, and he had continued paying the planned annual premium. Yet the updated in-force illustration showed that the policy was no longer projected to perform as originally illustrated.
The change from the 5.45% interest-crediting rate used in the original illustration to the 3.85% current rate used in the 2021 illustration materially affected the policy's projected values and longevity. Instead of building substantial policy value at later ages, the updated illustration projected that the coverage would lapse at approximately age 97 if the existing funding strategy continued under those assumptions.
That did not mean the policy needed to be replaced. The review identified several potential paths, including continuing to monitor the existing policy, increasing funding, adjusting the death benefit, or evaluating alternative coverage.
More importantly, the issue was identified early enough that Michael had time to consider those alternatives. Periodic life insurance policy reviews can help policy owners understand how an existing policy is performing, how changes in non-guaranteed assumptions may affect future results, and whether adjustments should be considered before a projected problem becomes more difficult to address.
Important Tax and Legal Information
This case study is provided for general informational and educational purposes only. Policy values, premiums, crediting rates, guarantees, and illustrated results described above relate to the particular policy and assumptions evaluated at the time of the review and should not be considered representative of current products or future results. Life insurance policy performance and available options depend on the specific contract and the policy owner's circumstances. Policy owners should review the applicable policy documents and consult appropriate insurance, tax, and legal professionals before making changes to existing coverage.