

A permanent life insurance policy can remain in force for years while gradually performing differently from the projections shown when the policy was originally purchased.
This does not necessarily mean something is wrong with the policy. Many permanent life insurance illustrations include both guaranteed and non-guaranteed elements, and actual policy performance can change as credited interest, dividends, policy charges, funding, and other policy factors develop over time.
Even relatively modest differences between original assumptions and actual experience can compound over many years. Depending on the type of policy and how it is funded, the result may be lower cash values, higher future premium requirements, a reduced death benefit, or coverage that is projected to terminate earlier than originally illustrated.
Understanding why that happens is an important part of evaluating permanent life insurance policy performance and determining whether the coverage continues to meet the policy owner's objectives.
Why Can Permanent Life Insurance Perform Differently Than Originally Illustrated?
Life insurance illustrations provide projections based on a combination of contractual guarantees and assumptions about future policy performance. The specific mechanics vary significantly among whole life, universal life, indexed universal life, and other forms of permanent coverage.
For that reason, an original illustration should not be viewed as a prediction of exactly how a policy will perform decades into the future. Instead, it provides a baseline that can later be compared with the policy's actual values and an updated in-force illustration.
Several factors can cause the results of an existing policy to differ from its original projections. These may include changes in non-guaranteed credited interest or dividends, policy charges, premium funding, withdrawals or loans, and changes made to the policy after it was issued.
Guaranteed and Non-Guaranteed Policy Elements
One of the most important distinctions when reviewing permanent life insurance is the difference between guaranteed and non-guaranteed policy elements.
Guaranteed elements are determined by the terms of the insurance contract. Depending on the type of policy, these may include guaranteed interest-crediting rates, maximum contractual charges, guaranteed cash values, or guaranteed death benefits when specified premium and other policy requirements are satisfied.
Non-guaranteed elements can change over time. Their effect depends on the type of life insurance policy and the provisions of the particular contract.
Universal Life Insurance
With traditional current-assumption universal life insurance, policy values are generally affected by interest credited to the policy and charges deducted by the insurance company. The contract establishes certain guarantees, including a minimum credited interest rate and maximum allowable charges, while the carrier may apply current rates and charges that are more favorable than those contractual guarantees.
An illustration based on current assumptions therefore shows how the policy is projected to perform if the illustrated assumptions continue. It does not guarantee that those assumptions will remain unchanged throughout the life of the policy.
If credited interest is lower than originally illustrated, or if applicable policy charges are higher than originally assumed, projected cash values and policy longevity may decline unless other factors offset the difference.
Whole Life Insurance
Participating whole life insurance works differently. The policy generally includes contractual guaranteed values based on the terms of the policy, while dividends are non-guaranteed and are determined by the insurance company.
Dividends may be used in several ways depending on the policy and the owner's election, including purchasing paid-up additional insurance, reducing premiums, accumulating with the insurer, or being received in cash.
Because dividends are not guaranteed, actual dividend performance can affect the non-guaranteed values shown in a whole life illustration. However, a whole life dividend rate should not be treated as equivalent to the interest-crediting rate of a universal life policy. The two products use different contractual structures and policy mechanics.
Why Small Changes in Non-Guaranteed Assumptions Can Matter
Changes in non-guaranteed assumptions may appear relatively modest when viewed one year at a time. Over a long period, however, those differences can compound and materially affect projected policy values.
This is particularly important with a current-assumption universal life policy because credited interest and policy charges interact with the amount of cash value available to support future policy costs. If policy values accumulate more slowly than originally illustrated, less value may be available to absorb increasing insurance costs at older ages.
An updated in-force illustration can help show the effect of those changes. Rather than relying on the assumptions used when the policy was purchased, the policy owner can compare the original illustration with the policy's current values and updated projections.
Universal Life Insurance Example: How Changing Assumptions Affected Policy Performance
Consider a universal life insurance policy issued in 2018 with a $500,000 death benefit and an annual premium of $5,228.
When the policy was originally issued, the non-guaranteed portion of the illustration used a 4.95% current interest-crediting rate. The illustration also showed contractual guaranteed values separately from the values projected using then-current assumptions.
What the Original Illustration Projected
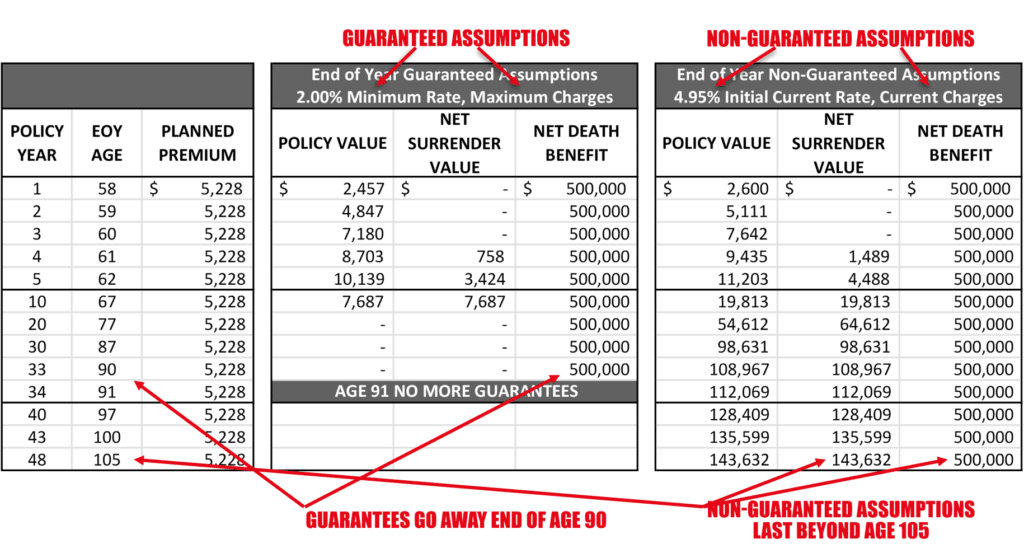
Under the assumptions used when the policy was issued, the $5,228 annual premium was projected to support the coverage well beyond age 105. The illustration ultimately projected coverage continuing to age 125 under the non-guaranteed assumptions shown at that time.
The policy also included a contractual death benefit guarantee through age 90, provided the applicable requirements of the guarantee were satisfied. This guaranteed result was separate from the longer-term values projected using non-guaranteed assumptions.
What the Updated Illustration Showed
Approximately two years later, the policy was reviewed using an updated in-force illustration. At that time, the current interest-crediting rate used in the illustration had declined from 4.95% to 4.55%.
Although the difference was only 0.40 percentage points, the updated projection showed a materially different long-term result when the existing $5,228 annual premium was maintained.
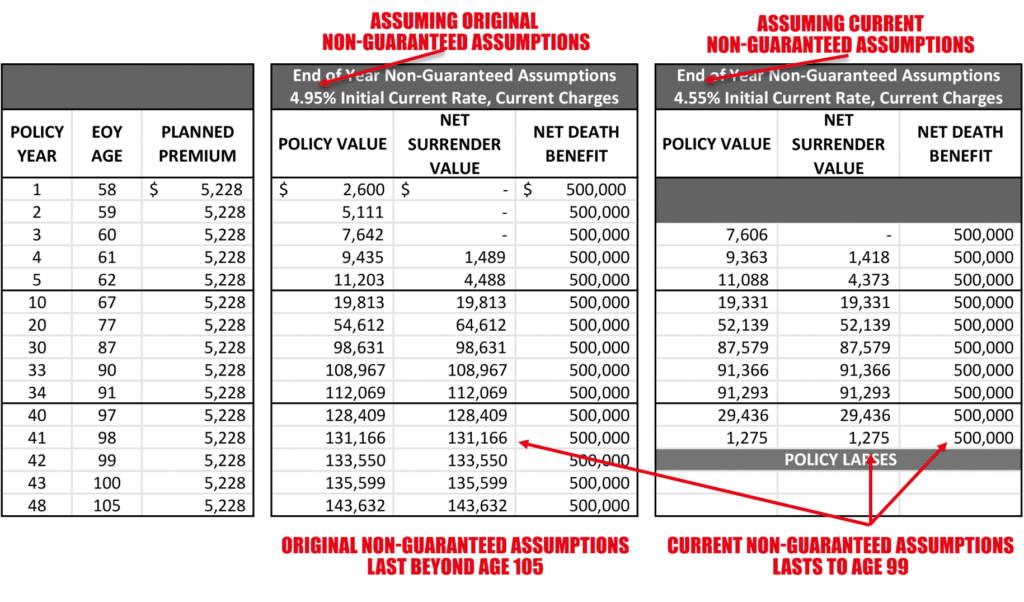
Under the updated assumptions, the policy was projected to lapse at approximately age 99. By age 98, the difference in projected policy value compared with the original illustration was approximately $130,000.
This did not mean the policy was certain to lapse at age 99. The updated illustration reflected the policy's values and assumptions at the time of the review. Future credited interest, policy charges, premium payments, and other policy activity could produce different results.
The comparison nevertheless illustrates an important point: relatively small changes in non-guaranteed assumptions can compound over long periods and materially change the projected performance of a permanent life insurance policy.
What Options May Be Available When a Policy Is Underperforming?
When an updated in-force illustration shows that a policy is no longer projected to perform as originally expected, the appropriate response depends on the policy owner's objectives, the terms of the contract, current policy values, and the reason for the change in projected performance.
In some cases, no immediate change may be necessary. In others, adjustments to premiums or the death benefit may help improve the policy's projected longevity. The important first step is understanding the available options and how each may affect the policy.
Continue the Existing Funding Strategy
One option may be to continue funding the policy as currently scheduled and monitor its performance over time. This may be appropriate when the updated projection still satisfies the policy owner's objectives or when there is sufficient flexibility to address future changes if necessary.
Choosing this approach does not mean assuming that future policy performance will improve. Periodic reviews can help determine whether the policy continues to remain consistent with the owner's objectives as actual experience develops.
Increase Premium Funding
Another option may be to increase the amount contributed to the policy. Additional premium can increase the policy value available to support future charges and may extend the projected duration of coverage, subject to the terms of the contract and applicable tax considerations.
In this historical example, an updated illustration showed that increasing the annual premium from $5,228 to approximately $5,467 was projected to restore coverage to age 125 under the assumptions being used at the time.
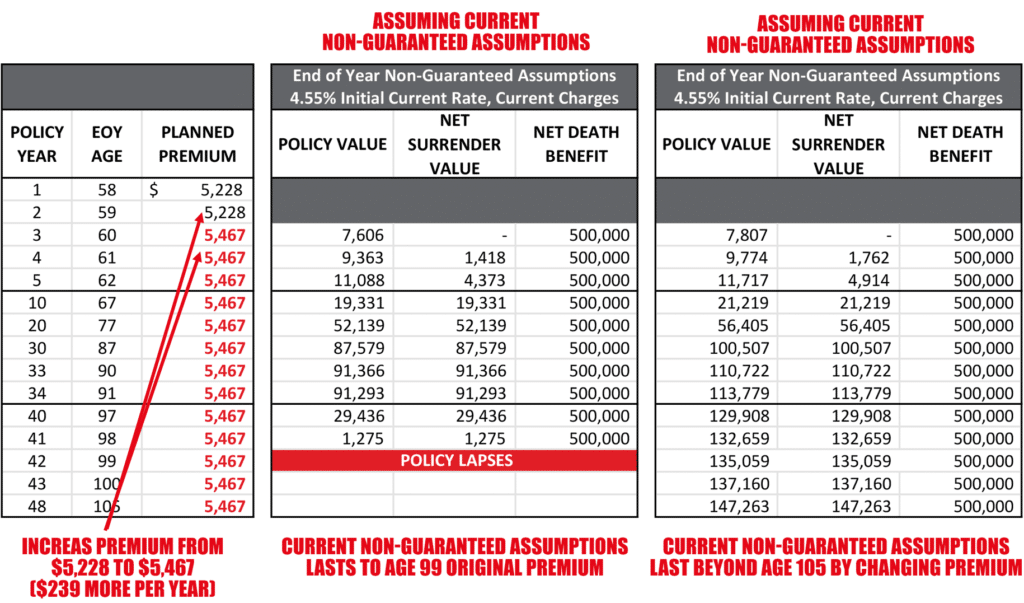
The additional $239 annual premium was relatively modest because the difference in projected performance was identified early. This does not mean the same adjustment would produce the same result in the future or for another policy. It illustrates why identifying a developing funding shortfall before it becomes severe can provide a policy owner with more flexibility.
Reduce the Death Benefit
Depending on the policy and the owner's insurance needs, reducing the death benefit may also improve projected policy longevity by reducing the amount of insurance being supported by the policy.
A death benefit reduction should not be evaluated solely as a way to improve policy performance. The policy owner should first determine whether the reduced coverage would still satisfy the estate planning, business planning, income replacement, or other objective for which the insurance is being maintained.
Evaluate Other Policy Alternatives
If the existing policy no longer meets the owner's objectives, it may also be appropriate to evaluate other alternatives. Depending on the circumstances, these could include modifying the existing contract or comparing it with other available coverage.
Any replacement or exchange requires a broader analysis than simply comparing illustrated values. Health and insurability, surrender charges, new contestability and suicide periods, policy guarantees, acquisition costs, tax consequences, and the loss of potentially valuable provisions in the existing contract should all be considered before making a change.
How Policy Charges Can Affect Universal Life Insurance Performance
Credited interest is only one factor that can affect the performance of a universal life insurance policy. Policy charges also play an important role because those charges are generally deducted from the policy value over time.
Depending on the contract, charges may include cost of insurance charges, administrative expenses, expense charges, and other policy-specific deductions. The amount and structure of these charges vary by product and insurance company.
Guaranteed Cost of Insurance Charges
A universal life insurance contract generally establishes maximum cost of insurance rates that the insurance company is permitted to charge. These contractual maximums are commonly reflected in the guaranteed portion of a policy illustration.
Cost of insurance charges are influenced by factors specified in the contract, which may include the insured's age, sex, underwriting classification, and the amount of insurance at risk. Because cost of insurance rates generally increase with attained age, these charges can become increasingly important to policy performance later in life.
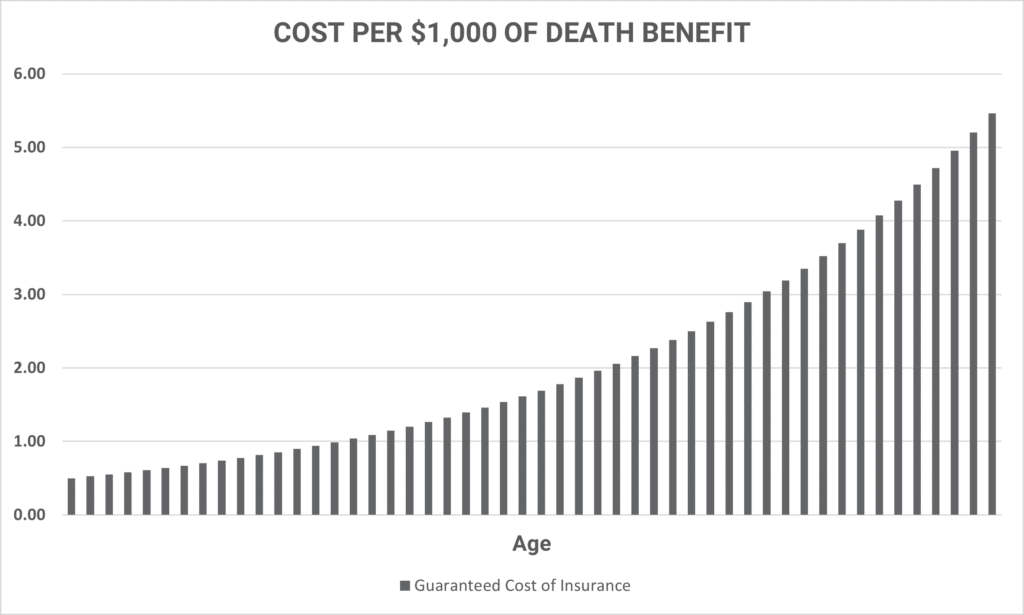
The guaranteed rates shown in the contract represent maximum contractual charges rather than a prediction of what the insurance company will necessarily charge throughout the life of the policy.
Current Cost of Insurance Charges
An insurance company may apply current cost of insurance rates that are lower than the contractual maximums. When a policy illustration uses current assumptions, those current charges can affect the policy values and longevity shown in the projection.
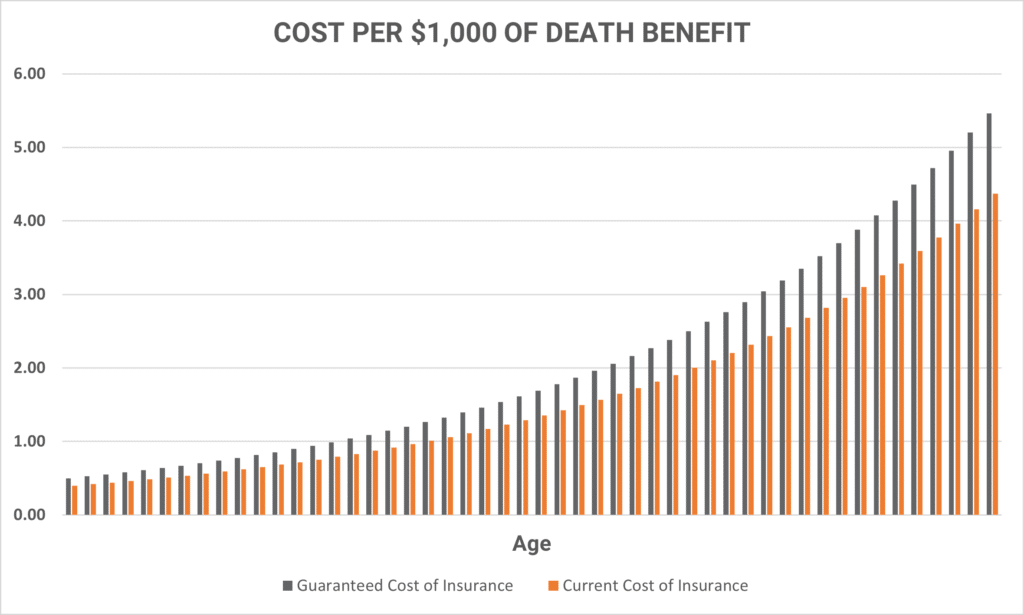
If applicable current policy charges change, the policy's future performance may also change. The extent of that impact depends on the terms of the contract, the policy's accumulated value, premium funding, death benefit, and other factors.
This is another reason an updated in-force illustration can be useful. A policy owner can evaluate the policy using the assumptions and charges reflected at the time of the review rather than relying exclusively on projections prepared when the policy was originally issued.
Why Permanent Life Insurance Policies Should Be Reviewed Over Time
The original illustration for a permanent life insurance policy represents a starting point, not a permanent forecast of how the policy will perform decades into the future.
As a policy ages, actual experience may differ from the assumptions used when the coverage was purchased. Credited interest, dividends, policy charges, premium funding, loans, withdrawals, and changes to the death benefit can all affect policy performance, depending on the type of coverage and the terms of the contract. In policies with significant outstanding loans, the interaction between policy values, loan interest, and ongoing policy charges can become particularly important to long-term performance.
For that reason, evaluating an existing policy should involve more than reviewing the most recent annual statement. A periodic life insurance policy review can compare current policy values with the original objectives for the coverage and use updated in-force illustrations to evaluate how the policy is projected to perform under different assumptions.
Identifying Policy Performance Problems Early
The universal life insurance example in this article demonstrates why timing can matter. The policy had not failed when it was reviewed. Instead, the updated illustration identified a developing difference between the original projection and the policy's projected future performance.
Because the issue was identified relatively early, the policy owner had several alternatives to evaluate, including maintaining the existing funding strategy, increasing premium payments, reducing the death benefit, or considering other policy alternatives.
A policy that is reviewed much later may present a different set of choices. Lower accumulated values, higher insurance costs at older ages, changes in health or insurability, outstanding policy loans, and fewer years available to adjust funding can potentially limit the alternatives available to the policy owner.
Permanent Life Insurance Policy Performance: Conclusion
A permanent life insurance policy performing differently from its original illustration does not necessarily mean the policy is failing or should be replaced. It means the policy should be evaluated based on its current values, contractual provisions, future projections, and the objectives it is intended to accomplish.
For some policy owners, the appropriate decision may be to continue the policy without changes. Others may determine that additional funding, a change in death benefit, or another strategy deserves consideration. The purpose of the review is to identify those choices while there is still sufficient time to evaluate them carefully.
Our life insurance policy review process is designed to help policy owners evaluate existing coverage, understand how a policy is currently performing, and assess whether the coverage remains aligned with its original planning objectives.
This material is provided for educational purposes only and is not intended as tax, legal, or investment advice. Life insurance policy guarantees are subject to the claims-paying ability of the issuing insurance company. Non-guaranteed policy values and assumptions may change. Policy owners should review their individual contracts and consult their professional advisors before making changes to existing coverage.


